Your Kid Has a Roth IRA?
(Yes, Really.)
My daughters, Olivia and Amelia, are 7 and 5. They cannot drive, cook dinner, or consistently remember where they left their shoes.
But they have retirement accounts.
When I tell you this was the thing that excited my husband most about acquiring this business, I mean it.
If you own a business, one of the more interesting ways to begin building generational wealth may be sitting right under your roof: legitimately employing your children and using their earned income to fund a custodial IRA.
First, Your Child Has to Actually Work
You cannot simply put your five-year-old on payroll for “consulting services” and call it a day.
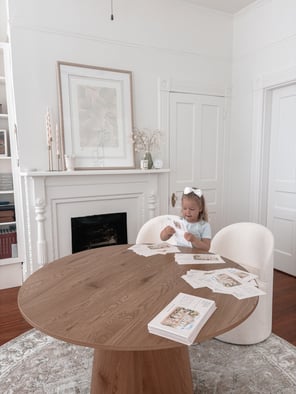
Amelia (5) is shown sorting mailers above, and there is so much more that children are capable of.
Your child needs to perform real, age-appropriate work for the business, and the compensation should be reasonable for the services performed. Think using them for your website or advertising, helping with appropriate office tasks, appearing in marketing materials, or other legitimate work that makes sense for your particular child and business.
Keep records. Document what they did, when they did it, and how you determined their compensation.
Federal law generally permits children to work for a business entirely owned by their parents, although restrictions still apply to manufacturing, mining, and hazardous work. Florida law also permits minors to work directly for their parents outside required school hours.
And because payroll and employment-tax rules vary depending on how your business is structured, this is absolutely a conversation to have with your CPA before adding them to payroll.
For example, wages paid to children under 18 by a parent's sole proprietorship (or certain partnerships owned by the parents) can be exempt from Social Security and Medicare taxes. That exemption does not apply the same way when the employer is a corporation.
Then Comes the Fun Part: The Roth IRA
Once your child has legitimate earned income, a parent can establish a custodial IRA for them.
For 2026, the maximum contribution to traditional and Roth IRAs is $7,500, or the child's taxable compensation for the year, whichever is less. So if your child legitimately earns $3,000, up to $3,000 can generally go into an IRA.
For young children, a Roth IRA can be particularly compelling because they are often paying little or no federal income tax today. Roth contributions do not produce an income-tax deduction now, but qualified withdrawals in retirement can be tax-free.
And the parent can provide the money for the contribution. Your child does not necessarily have to surrender every dollar of their paycheck to their 60-year-old self.
Why Start at Age 5?
One word: time.
Imagine putting $3,000 into an account for a child and giving that money 60+ years to grow.
The goal is not simply to leave our children an inheritance someday. It is to give them a head start while we are still here to teach them what to do with it.
That is one of my favorite ways to think about generational wealth: not just transferring money when we die, but intentionally creating opportunities during our lifetime.
Olivia and Amelia may not appreciate their retirement accounts right now. Frankly, they would probably prefer Squishmallows.
Future Olivia and Amelia may feel differently.
Do Not Forget the Estate-Planning Piece
A custodial IRA is still part of the bigger financial picture.
Florida's Uniform Transfers to Minors Act specifically recognizes retirement plans and IRAs within its definition of a “benefit plan,” and Florida law governs many issues involving property held for minors.
As your family builds wealth, make sure your estate plan, beneficiary designations, custodial accounts, trusts, and financial accounts actually work together.
And remember: opening the account is only step one. Someone still has to invest the money inside the account.
The Takeaway
If you are a business-owning parent, ask your CPA:
“Can my children legitimately work in my business, and can we use some of that earned income to begin funding Roth IRAs for them?”
Then make sure your estate-planning attorney knows what you are doing so those accounts fit into your family's overall plan.
Because a good estate plan is not only about what happens to your money someday. It is about using what you have built to give the next generation a head start.
Questions? Schedule a complimentary 10-minute phone call with an attorney to discuss.

Sincerely,
Amanda “Always Thinking Ahead” Lynch Elliott
Note: This article is general educational information, not individualized tax or legal advice. Employment, payroll, IRA, and tax rules depend heavily on your business structure and circumstances. Work with your CPA and financial advisor before implementing a strategy for your family.